

Hotel vs Villa Tax in Bali: How Property Use Affects Tax
At a glance: Hotel vs villa tax in Bali depends on the property’s actual use and transaction model, rather than its building name. This article compares those classifications. For the wider rules, see our hotel PBJT guide and, for property arrangements, our villa lease and accommodation tax guide. Support is available through hotel tax reporting services.
Hotel vs villa tax in Bali is a frequent question among accommodation owners, property investors, and Airbnb operators. Although the same local tax framework may apply, taxable activities, business permissions, and reporting arrangements need to be assessed against the actual operation.
Misunderstanding these requirements can cause administrative penalties, licensing problems, and operating difficulties. Tax classification should therefore be considered before launching an accommodation business.
What Is Hotel Tax?
Hotel tax is a local tax on accommodation services supplied by hotels, resorts, guest houses, homestays, and other qualifying providers.
Under the current framework, it falls within hotel-service PBJT, the tax on certain goods and services.
The relevant services may include:
- Room accommodation.
- Lodging services.
- Supporting hotel facilities.
- Certain additional services.
A 10% rate is commonly encountered, but the rate and taxable base must be confirmed in the applicable regency or city regulation.
What Is Villa Tax?
A villa used commercially for accommodation, especially daily or weekly guest stays, can fall within hotel-service PBJT.
A villa used only as a private residence normally has no accommodation-service PBJT transaction merely because it exists. Other property-related obligations may still apply.
The distinction begins with actual use:
Private Villa
The property is not operated as a commercial accommodation business.
Commercial Villa
The property is used for:
- Airbnb accommodation.
- Daily bookings.
- Weekly guest stays.
- Tourist accommodation.
Applicable requirements generally include:
- Appropriate business permissions.
- Collection of accommodation tax where taxable.
- Local tax reporting.
Read Also: Bali Hotel PBJT: Taxable Services, Records and Local Reporting
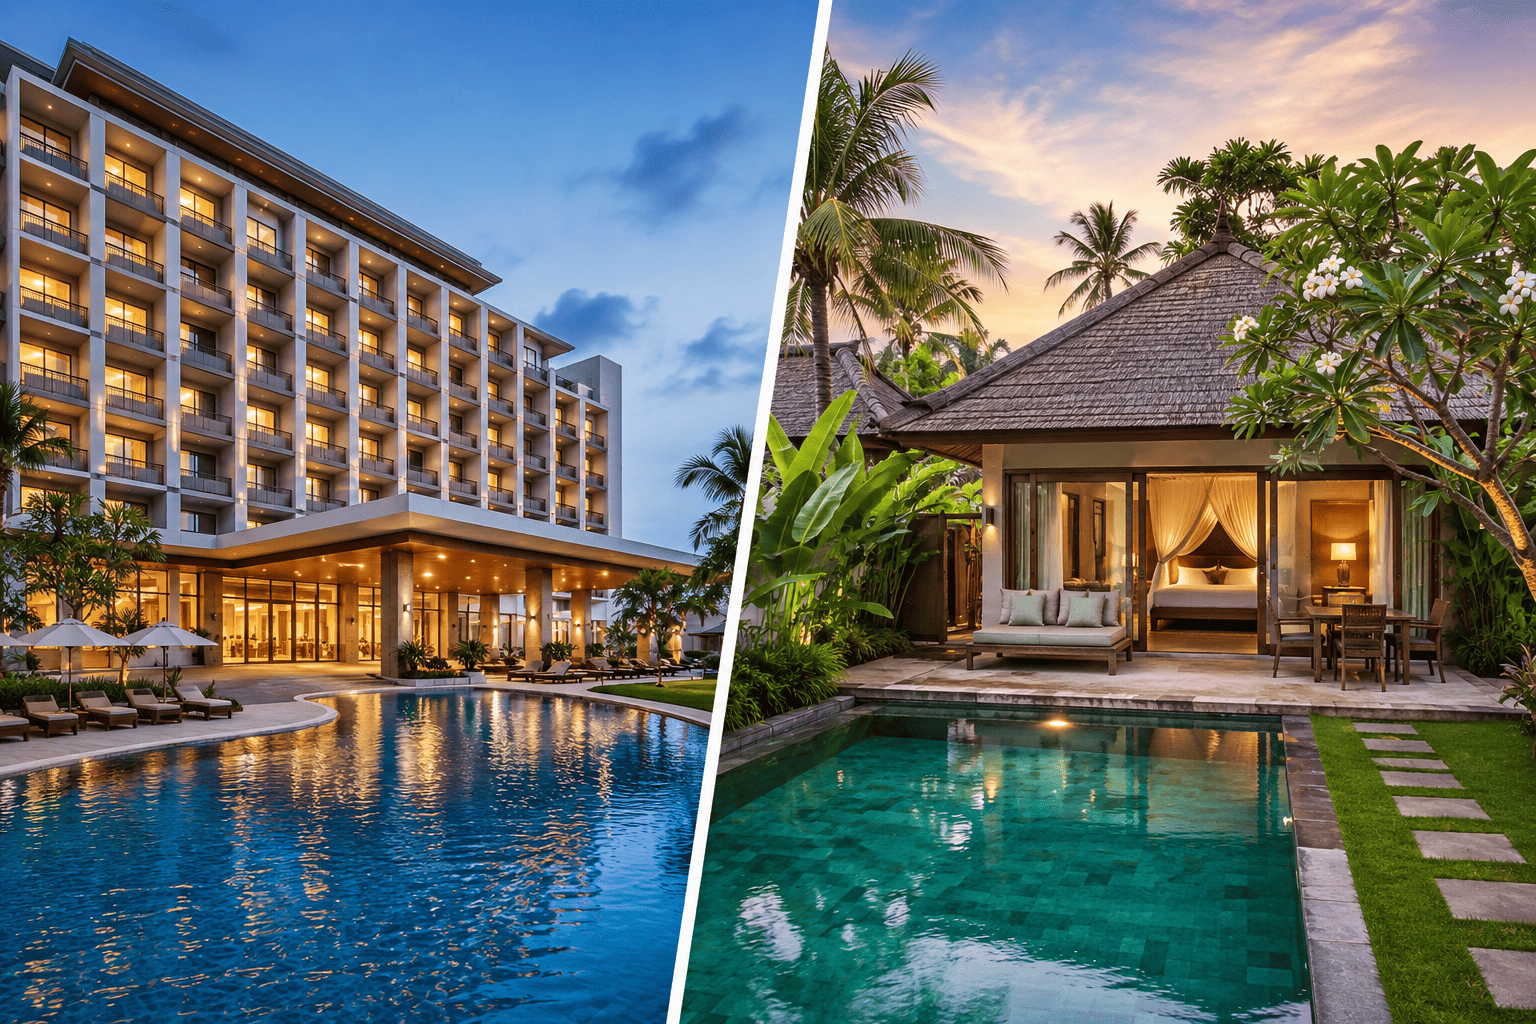
Hotel vs Villa Tax in Bali: Key Differences
1. Business Legality
A hotel needs the permissions and standards applicable to its accommodation activity.
A villa may instead be:
- A private property.
- An investment property.
- A tourist accommodation business.
Regular commercial guest accommodation can bring a villa within accommodation-business requirements. The activity and legal arrangement must be reviewed.
2. Taxable Activities
A hotel’s qualifying accommodation services fall within the hotel-service tax rules.
For villas, relevant indicators include:
- Commercial rental activity.
- Recurring income.
- Marketing through online platforms.
These are indicators rather than standalone legal tests. A genuine property lease must be distinguished from guest accommodation.
3. Tax Supervision
Hotel operations commonly produce records through:
- Formal reservation systems.
- Larger room inventories.
- Professional operating processes.
Villa activity may also be visible through:
- OTA platforms.
- Airbnb records.
- Local supervision in tourism areas.
Neither business type should assume that its size or platform prevents review. Our introduction to OTAs for Bali hotels and villas explains the booking data involved.
4. Tax Calculation
Hotels and commercial villas supplying the same taxable accommodation service may face the same local PBJT rate, often illustrated as 10%.
The practical calculation nevertheless depends on:
- The business activity.
- The booking system.
- The legal structure and supporting records.
- The relevant local provisions.
Are Airbnb Villas in Bali Taxable?
A commercially operated Airbnb villa can be subject to local accommodation tax because the underlying activity is a guest accommodation service.
Owners should address:
- Local taxpayer registration, including NPWPD where required.
- Business permissions.
- Tax reporting.
- PBJT payment.
Risks of Ignoring Villa Tax
Depending on the breach and applicable procedure, risks can include:
- Administrative penalties.
- Local tax examination.
- Operating restrictions or closure where legally authorized.
- Licensing difficulties.
- Property or business legality problems.
Owners should understand the obligations from the beginning of operations.
When Is a Villa Treated as an Accommodation Business?
Indicators include:
- Daily guest stays.
- Hotel-like services.
- Public marketing.
- Recurring accommodation income.
- A reservation system.
Professional guest operations can indicate a taxable accommodation activity. Classification still depends on the legal rules and facts, not simply how polished the business appears.
Tips for Managing Hotel and Villa Tax in Bali
Separate Personal and Business Finances
This makes tax reporting easier to trace.
Use a Bookkeeping System
Transaction records help prevent reporting errors.
Address Legal Requirements Early
Appropriate business permissions reduce legal uncertainty.
Consult a Tax Adviser
Professional support helps interpret current rules.
Tax Reporting Support in Bali
Understanding the rules early helps hotel, villa, and accommodation owners operate with better compliance controls.
Usman Tax can assist with:
- Hotel and villa tax.
- NPWPD administration.
- Local tax reporting.
- Business legality coordination.
- Tax support for tourism businesses.
The business advisory team can help coordinate the administrative issues relevant to the operating model.
FAQ Hotel vs Villa Tax in Bali
What is the main difference?
The property’s use and transaction model matter most. Commercial accommodation can bring a villa within the same PBJT framework as a hotel, while a genuine lease or private use needs a different assessment.
Is a private villa subject to hotel tax?
Normally no accommodation-service PBJT arises if it is used privately and no taxable service is supplied. Other property taxes may remain relevant.
What hotel tax rate applies in Bali?
A 10% rate is commonly encountered, but verify the relevant local regulation.
Must Airbnb accommodation pay tax?
The underlying accommodation business must meet the tax obligations applicable to its activities.
Can a guest house fall within hotel services?
Yes, qualifying guest-house accommodation can fall within the local tax category.
What is hotel PBJT?
It is PBJT applied to qualifying hotel and accommodation services.
Is a monthly villa rental subject to hotel tax?
It depends on the actual agreement, services, and applicable rules. Duration alone does not settle the classification.
Who collects hotel tax?
The accommodation business or operator responsible under the relevant rules.
What if villa tax is ignored?
Penalties, examination, and business legality problems may follow.
How should an owner start?
Review business permissions, local taxpayer registration, and periodic reporting requirements.
Conclusion
Hotel vs villa tax in Bali turns on business use, legal arrangements, and the services supplied. A commercially operated villa can fall within hotel-service PBJT, particularly for tourist stays.
Understanding the rules early helps owners reduce legal problems and manage operations professionally.
For help with accommodation tax administration, contact Usman Tax through its hotel tax reporting services.