Hotel PBJT Classification: Hotel Service Transactions Before Filing
Main topic: Classifying hotel services subject to PBJT and the exclusions before determining the tax base.
Full background: Bali Hotel PBJT: Tax Objects, Data and Local Tax Reporting.
Continue according to your needs: Hotel PBJT versus Hotel VAT: Understanding the Differences (Indonesian) and Bali Hotel Tax Rates and Calculation Checks.
Support is available through our hotel tax reporting service.
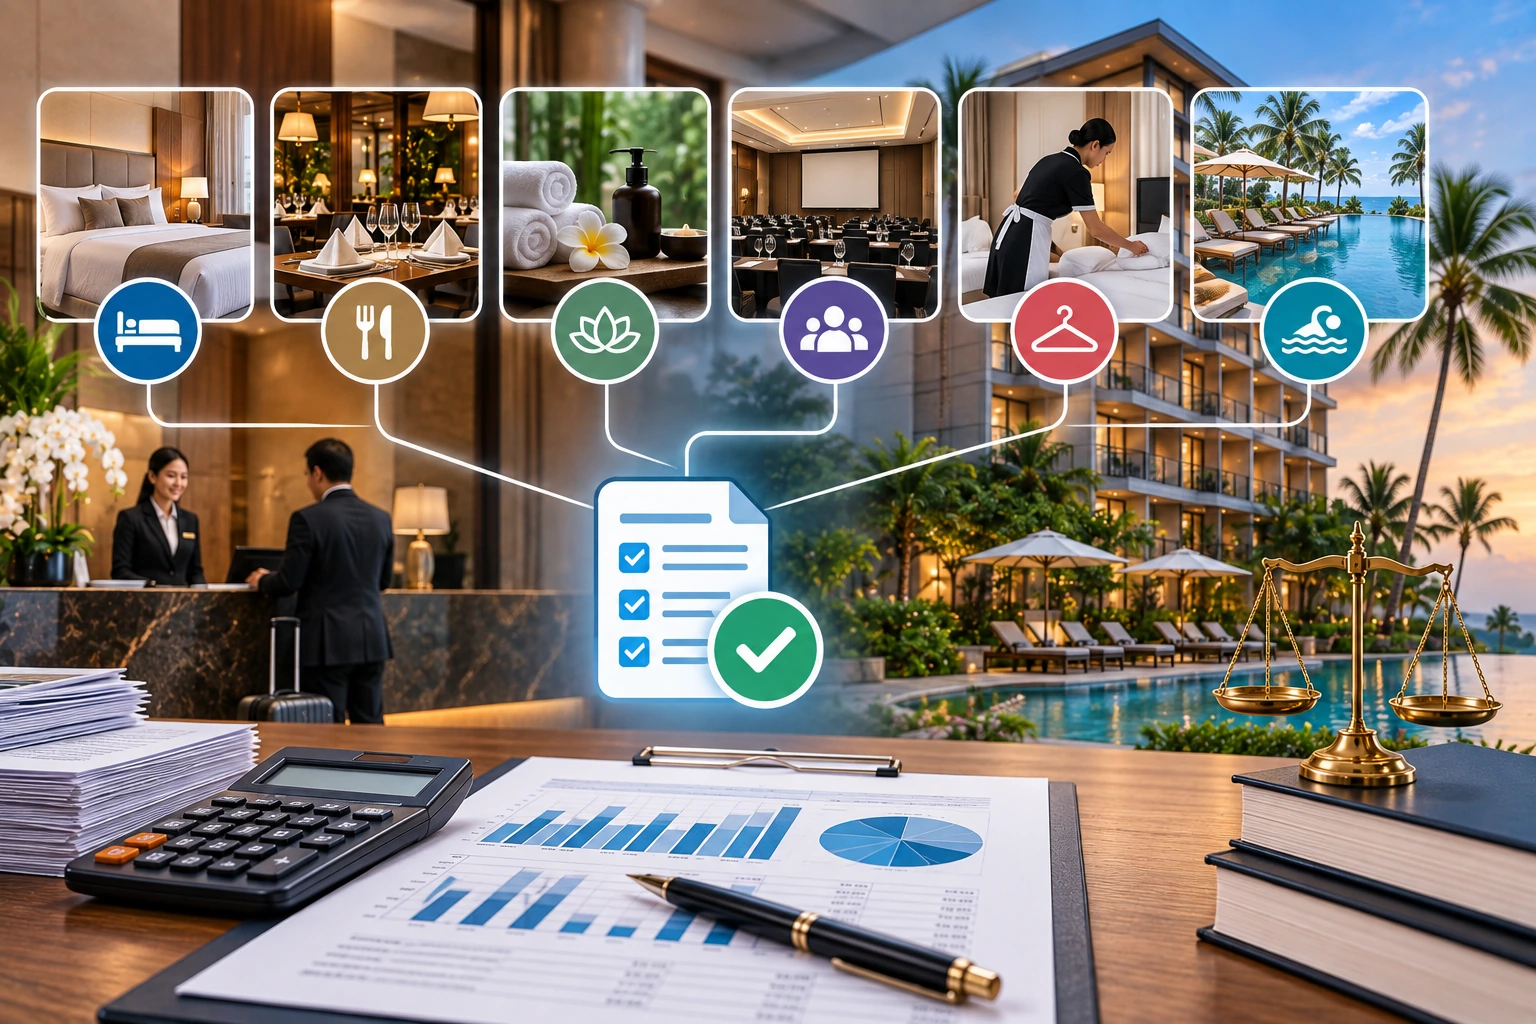
A hotel should not calculate PBJT by adding every receipt together and putting the total into one category. A single operation may include rooms, meeting spaces, restaurants, minibars, spas, third-party outlets, deposits, refunds and OTA transactions with different characteristics.
The first step in hotel PBJT classification is to determine which transactions are hotel services subject to PBJT, which fall into other PBJT categories, which are excluded and which require analysis of their actual facts.
Under Law 1 of 2022, PBJT covers the sale, supply or consumption of specified goods and services, including hotel services.
Hotel PBJT Classification: Which Services Are Included?
Article 53 of Law 1 of 2022 includes accommodation and supporting facilities, as well as meeting or conference room rentals at hotel service providers. Examples include hotels, hostels, villas, tourist lodgings, motels, inns, tourist guest lodgings, guesthouses, bungalows, resorts, cottages, private residences operated as hotels and glamping accommodation.
The analysis therefore goes beyond a business licence containing the word “hotel”. Villas, guesthouses, resorts, glamping and other accommodation forms named in the law can also fall within hotel services.
Accommodation and Supporting Facilities
Room revenue is the clearest hotel example. However, the provisions also cover supporting facilities associated with accommodation.
In practice, finance still needs to examine how a facility is offered, paid for and recorded. Do not determine the tax category solely from account names such as other hotel revenue or guest service.
A useful transaction map is:
Reservation/folio → service type → amount paid → data source → general ledger account → PBJT category → working paper.
Meeting Rooms Are Included, but Premises Let for Another Business Are Excluded
This distinction matters.
The law includes meeting or conference room rentals at hotel service providers within hotel services. It also expressly excludes premises rented out for business operations within a hotel.
For example, a meeting room supplied by the hotel to a guest or company needs to be distinguished from space let to another party to operate a shop, office, clinic or other business.
Do not decide the treatment merely from the term “space rental”. Examine the user, purpose, contract, invoice and actual service provided.
Which Services Are Excluded from Hotel Services?
The same law excludes specified services from the hotel services category, including:
- dormitory accommodation provided by central or local government;
- accommodation in hospitals, nurses’ residences, elderly care homes, orphanages and similar social institutions;
- accommodation at educational centres or for religious activities;
- travel agency or tour services; and
- premises rented out for business operations within a hotel.
These exclusions show that a transaction taking place inside a hotel does not automatically make it subject to PBJT as a hotel service.
Do Not Put Every Hotel Revenue Stream into One PBJT Category
A hotel can conduct several types of transactions within the same property. For traceable reporting, its chart of accounts and operational systems should distinguish those revenue sources.
Restaurants, Room Service, Minibars and Banquets
Food and beverages form a separate PBJT category under the central–local financial relations law. Restaurant transactions should therefore not automatically be combined with room revenue simply because the customer is a hotel guest.
The same review is needed for room service, minibars, banquets, room packages including breakfast and food sold to visitors who do not stay overnight. Examine the actual service and package arrangements before settling the classification.
The Bali hotel restaurant PBJT guide discusses PMS and POS separation, room packages, breakfast, minibars, banquets, deposits and restaurant transactions in more detail.
Spas, Entertainment and Third-Party Outlets
Spas and specified entertainment activities should not automatically be included in hotel services. The law has a separate PBJT category for arts and entertainment services.
For a third-party outlet, distinguish hotel operating revenue, space rental, revenue sharing and other transactions. Read the contract, invoice, identity of the service provider and payment flow together before deciding the classification.
Hotel PBJT Classification Matrix
This table provides an initial control before transactions enter the working papers. It is not an official classification for every possible set of facts.
| Transaction | Initial Review | Data to Examine |
|---|---|---|
| Hotel room | Hotel services | PMS, folio and invoice |
| Commercial villa or guesthouse | Hotel services if the relevant transaction conditions are met | Reservation, contract and folio |
| Hotel meeting room | Hotel services | Event order, invoice and folio |
| Hotel restaurant | Food and/or beverage PBJT if the requirements are met | POS, bill and invoice |
| Room service/minibar | Review the food or beverage transaction and its service context | PMS/POS and folio |
| Spa or entertainment | Review the relevant PBJT category | POS, invoice and service type |
| Space let for another party’s business | Excluded from hotel services under Article 53 | Lease agreement and invoice |
| Guest deposit | Cash receipt alone is insufficient to determine the tax category | Deposit ledger, booking and folio |
| Refund | An adjustment to the original transaction, rather than a separate tax category | Refund report and original transaction |
| OTA settlement | A payment channel or method, rather than a separate tax category | OTA report, folio and bank statement |
The implication is that finance needs to classify transaction substance before payment method. One bank transfer or OTA settlement may contain several transaction types.
Deposits, Refunds, OTAs and Bank Accounts Are Not Tax Categories
A common error is treating the payment method as the basis for tax classification.
A deposit does not automatically become a separate taxable item because money has been received. Review reservation status, the hotel’s rights and obligations, potential refunds and how the payment relates to the service provided.
A refund is not a new tax category either. Finance needs to trace the original transaction and ensure reversals in PMS, POS, bank and ledger records are consistent.
An OTA is a distribution channel. Gross bookings, commissions, refunds, adjustments, settlements and bank receipts need to be reconciled before figures are used in working papers.
Accordingly, total bank account credits cannot replace PBJT transaction classification.
Who Is the PBJT Taxpayer for Hotel Services?
Articles 56 and 57 of Law 1 of 2022 identify consumers as the persons subject to PBJT, distinguish the individual or entity carrying out the sale, supply or consumption as the taxpayer with the statutory obligations, and establish consumer payments as the tax base.
Under Government Regulation 35 of 2023, PBJT on hotel services is a regency/city tax collected through taxpayer self-assessment.
For private residences operated as hotels and marketed through third parties, the explanation to Law 1 of 2022 identifies the PBJT taxpayer as the owner or party controlling the residence who supplies accommodation to the end consumer, rather than the digital platform marketing or management service provider.
The presence of an OTA or platform therefore does not automatically transfer taxpayer status to the platform.
Scope of a Hotel PBJT Classification Review
For a hotel with several revenue sources, the review may cover:
| Area | Work | Output |
|---|---|---|
| PMS | Separate rooms, packages, complimentary stays, adjustments and refunds. | Room transaction map |
| POS | Separate restaurants, minibars, room service, banquets and relevant spa/outlet transactions. | Outlet transaction map |
| Contracts | Review meeting rooms, tenants, space rentals and revenue sharing. | List of transactions requiring classification |
| OTA | Match bookings, refunds, commissions and settlements. | OTA reconciliation |
| Bank | Identify guest payments and non-revenue transactions. | Bank matching |
| General ledger | Match revenue codes with transaction categories. | Revenue-to-tax mapping |
| PBJT | Prepare working papers using reviewed categories. | Data supporting the return |
This is an example review scope, rather than an official local government format.
Usman Tax’s hotel tax reporting service in Bali includes matching operational hotel reports with tax reports, allowing classification work to feed into reconciliation and filing.
Data to Prepare Before Classification
Commonly useful records include:
- PMS or reservation reports;
- guest folios;
- restaurant and outlet POS records;
- room package lists;
- banquet/event orders;
- tenant or space rental contracts;
- OTA reports;
- refund and cancellation reports;
- the deposit ledger;
- bank statements;
- the general ledger;
- the chart of accounts; and
- the PBJT working papers currently in use.
Not every case requires every document. Select records relevant to the transaction being classified.
When Does a Hotel Need Further Review?
A more detailed review is worth considering when:
- all receipts are still recorded as room revenue;
- PMS and POS records are not clearly separated;
- the hotel has a restaurant, spa, tenants and meeting rooms;
- room packages include breakfast or additional services;
- OTA figures differ from accounting revenue;
- deposits and refunds frequently move between periods;
- the treatment of tenant or revenue sharing contracts is unclear;
- PBJT working papers cannot be reconciled with the general ledger; or
- the hotel operates in several regencies or cities.
Check rates, forms, deadlines and filing portals for the regency or city where the business is located. This article does not establish one local procedure for all of Bali.
Conclusion
Hotel services subject to PBJT are not the same as all revenue generated inside a hotel. Law 1 of 2022 includes accommodation, supporting facilities and specified meeting or conference room rentals, while also providing exclusions and separate PBJT categories for different transactions.
A sound sequence is classify transactions → identify data sources → reconcile PMS/POS/OTA/bank records → map to the general ledger → prepare PBJT working papers.
This structure helps owners see which transactions belong to hotel services, which need separation and which require further review before filing.
Still Unsure Which Transactions Fall Within Hotel Services PBJT?
If room, restaurant, meeting room, tenant, deposit, OTA and other outlet figures remain mixed in hotel reports, begin by mapping each transaction to its source data and tax category before preparing the SPTPD local tax return.
Usman Tax provides hotel tax reporting services and accounting services for hospitality businesses in Bali. A consultation can cover transaction classification, PMS/POS/OTA reconciliation, PBJT working papers and filing data readiness based on actual hotel operations.
FAQ Hotel PBJT Classification Before Filing
Which Hotel Services Are Subject to PBJT?
Law 1 of 2022 includes accommodation and supporting facilities, as well as meeting or conference room rentals at hotel service providers. Examples include hotels, hostels, villas, tourist lodgings, motels, inns, tourist guest lodgings, guesthouses, resorts, cottages, private residences operated as hotels and glamping.
Are Hotel Restaurant Transactions Classified as Hotel Services PBJT?
Food and beverages form a separate PBJT category. Restaurant, room service, minibar and banquet transactions need to be identified and reviewed under the relevant food and beverage provisions and their actual service context, rather than automatically mixed into room revenue.
Does a Hotel Meeting Room Fall Within Hotel Services?
Yes. Law 1 of 2022 includes meeting or conference room rentals at hotel service providers within hotel services.
Does Renting a Shop or Business Premises Inside a Hotel Count as Hotel Services?
Law 1 of 2022 expressly excludes premises rented out for business operations within a hotel from hotel services. The contract and actual use still need review to determine the transaction’s overall treatment.
Does a Guest Deposit Immediately Become Subject to PBJT?
Receipt of money alone is insufficient to determine treatment. Examine reservation status, rights and obligations towards the guest, refundability, the folio and how the payment relates to the service provided.
Is the OTA Settlement Amount the Hotel PBJT Base?
Not automatically. Settlements may reflect commissions, refunds, cancellations, adjustments or payment timing. Reconcile bookings and actual transactions before determining the figure used in working papers.
Who Is the PBJT Taxpayer When a Hotel Is Marketed Through an OTA?
An OTA does not automatically become the taxpayer. For private residences operated as hotels, the explanation to Law 1 of 2022 identifies the owner or controlling party supplying accommodation to the end consumer, rather than the marketing or management platform.
Are Hotel PBJT Rates Identical Throughout Bali?
Rates and administration follow the relevant regency or city’s local rules. Check the applicable local regulation and Bapenda guidance, rather than borrowing a rate or portal from another area.
Sources and References
- Law 1 of 2022 on Financial Relations between Central and Local Governments
- Law 1 of 2022: Ministry of Finance JDIH Status Record
- Government Regulation 35 of 2023 on General Provisions for Local Taxes and Levies
- Government Regulation 35 of 2023: Ministry of Finance JDIH Status Record
- Usman Tax Hotel Tax Reporting Services in Bali
- Usman Tax Bali Hotel Restaurant PBJT Guide
- Usman Tax Bali Hotel PBJT Guide
Read Also: Hotel Tax Documents: A Checklist for Finance Teams
Read Also: Bali Hotel PBJT: Tax Objects, Data and Local Tax Reporting