

Villa Lease vs Management Fee Tax: PPh 4(2) and PPh 23
Main topic: Distinguishing land/building rental income from villa management service fees under the contract.
Complete foundation: Villa Tax Reporting in Bali: An Owner and Operator Guide.
Continue as needed: Villa Management Fee PPh 23: Rates, Withholding Base and Examples, Villa Property Rental Tax in Bali: Final Income Tax, Leasehold and Commercial Villas.
Assistance is available through villa management tax reporting services.
Villa lease vs management fee tax, including PPh Article 4(2) and PPh 23, is not about selecting the lower rate. They apply to different income types, so first establish what transaction is actually being paid for.
One relationship between a villa owner, operator and manager can include land/building rental, management fees, vehicle or equipment rental, reimbursements and accommodation activities. These do not automatically receive the same income tax treatment.
PPh Article 4(2) vs PPh 23 for Villas: The Main Difference
For genuine land and/or building rental, Government Regulation 34 of 2017 makes the relevant rental income subject to final income tax.
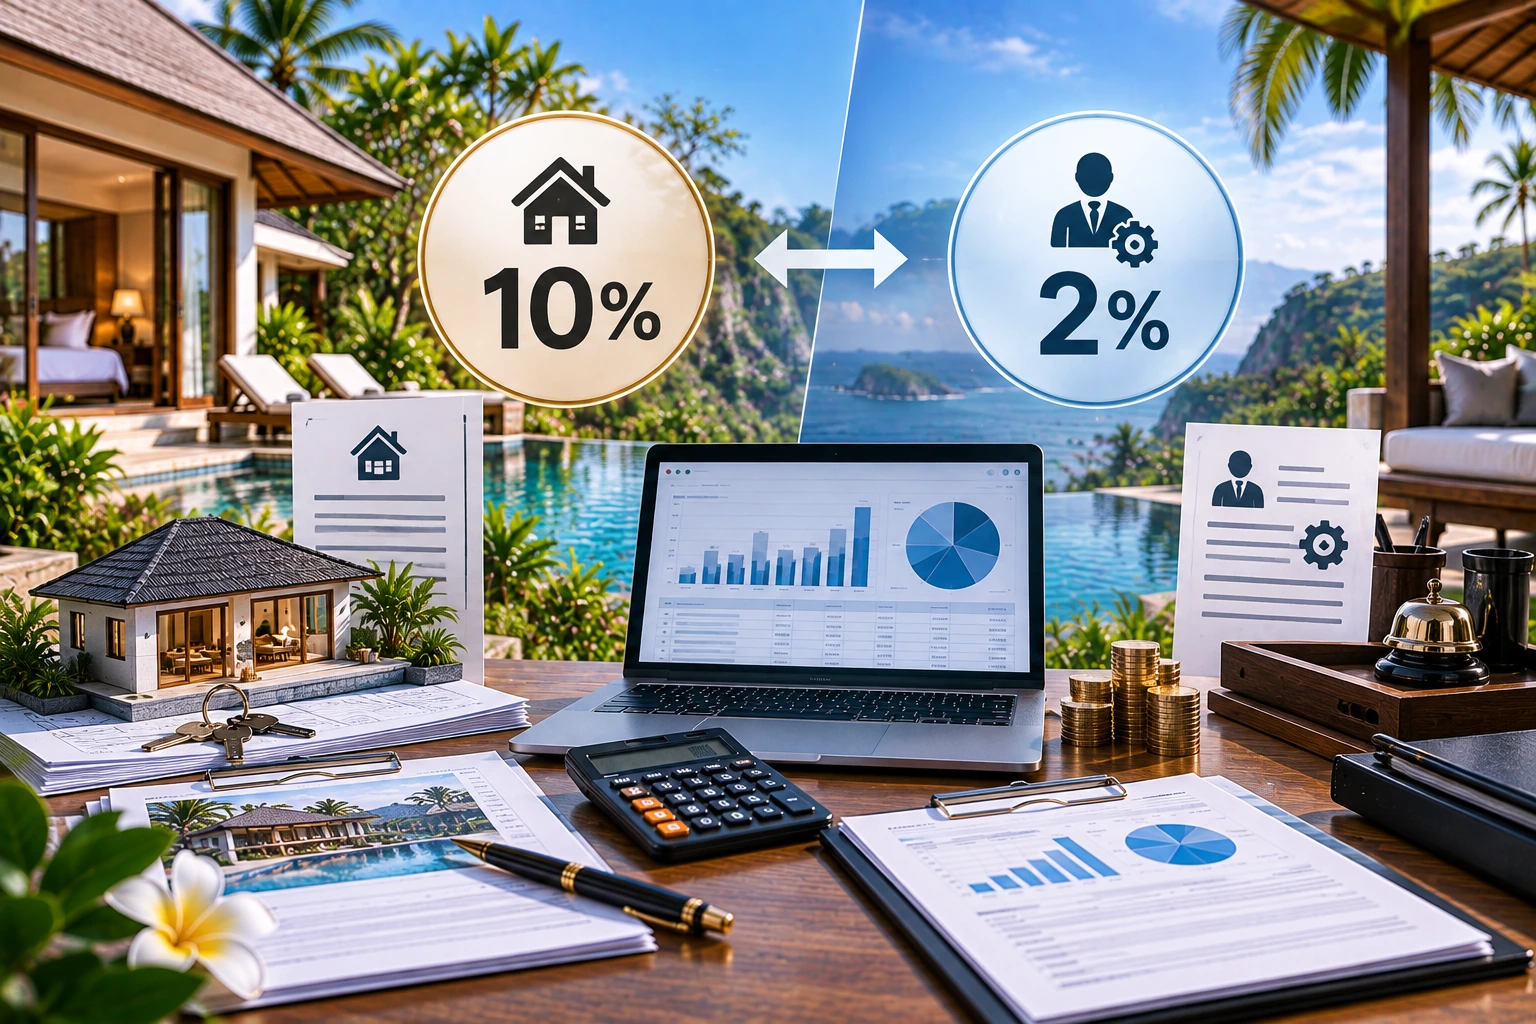
Under that regime, the final income tax rate is 10% of the gross land and/or building rental value.
PPh Article 23 has a different scope. DJP’s official explanation states that 2% withholding on gross amounts covers qualifying rentals and other income from assets outside Article 4(2), and technical, management, consulting and other qualifying services.
Article 4(2) for land and building rental
If an owner rents villa land and buildings to another party through a genuine property lease, Government Regulation 34 of 2017 is the analytical starting point.
A villa supplied to guests as accommodation therefore must not automatically be treated like an owner leasing a building to an operator or tenant under a property contract.
Article 23 for certain asset rentals and services
Article 23 may be relevant when payment is for other asset use or management services rather than land/building rental already within final income tax.
DJP also explains that Article 23 is withheld on income paid, made available for payment or due from an Article 23 withholding party to a domestic taxpayer or permanent establishment.
For services outside the main categories, PMK 141/PMK.03/2015 defines other services within Article 23 using a 2% gross-amount rate under its provisions.
Before withholding, examine the payment type, recipient and whether the payer has a withholding obligation.
Seven Differences to Check
This comparison supports initial screening. Actual analysis still needs the contract and transaction facts.
| Factor | PPh Article 4(2) | PPh Article 23 |
|---|---|---|
| Main focus | Land and/or building rental. | Certain asset rentals outside final income tax and certain services. |
| Villa example | A lease of villa land and buildings. | Management fees or qualifying use of assets other than land/buildings. |
| Rate discussed here | 10% final tax for land/building rental. | 2% of gross amounts for relevant rental/service categories. |
| Tax nature | Final for rental income within Regulation 34/2017. | Article 23 withholding according to income type and relevant parties. |
| Decision basis | The substance of a land/building lease. | The substance of asset rental or services. |
| Accommodation services | Excluded from Regulation 34/2017’s rental scope. | Not automatically Article 23; further classification is needed. |
| Main checks | Lease contract, property and gross rent. | Service/asset contract, recipient, withholding party and gross payment. |
Do not choose Article 4(2) or Article 23 merely by comparing 10% with 2%. Rates follow transaction classification, not the reverse.
Villa Transaction Decision Matrix
Use this screening matrix before preparing withholding certificates or tax entries.
| Transaction | Initial Analysis | What to Verify |
|---|---|---|
| Owner leases villa land and buildings to an operator. | Article 4(2). | Lease substance, tenant and gross amount. |
| Villa manager receives a management fee. | Potential Article 23. | Service substance, domestic/permanent establishment recipient and payer’s withholding obligation. |
| Company rents vehicles or equipment for villa operations. | Potential Article 23. | Asset type, recipient and withholding status. |
| Villa receives guest payments for stays. | Do not automatically apply final building rental tax. | Accommodation classification and other relevant taxes. |
| Invoice combines property rent and management services. | Separate transaction substance. | Contract, invoice breakdown and each component’s value. |
This does not mean every management fee or asset rental has identical withholding. Check recipient status, payer and contractual substance before determining treatment.
Example Owner and Villa Management Structures
Suppose owner A has a villa and appoints PT B as villa manager.
Several structures are possible.
Under a lease model, PT B rents the land and buildings and operates accommodation for its own account. Analyse lease payments to the owner as land/building rental under Regulation 34 of 2017.
Under a management model, the owner remains the main economic party in operations and PT B earns a management fee. That fee does not automatically follow final property rental tax merely because the business concerns a villa. Where it is a management service and Article 23 requirements are met, the analysis shifts to Article 23.
A mixed model can contain leases, management fees, reimbursements and other asset use together. Separate each payment flow according to contract and substance.
This is why a villa expense account name or one combined invoice is insufficient to determine tax type.
Documents to Match Before Withholding
Before determining income tax, examine:
- Lease or management agreements.
- Payer and recipient identities.
- Invoices and payment component details.
- The rented asset.
- Descriptions of services.
- The general ledger.
- Bank payment evidence.
- Previously issued withholding certificates.
- Owner statements where villa management is used.
- Reimbursement documentation, if any.
Contracts, invoices, payments and the ledger should use consistent classifications. If a contract says management fee while the ledger says building rental, resolve the difference before determining tax treatment.
Common Mistakes
Applying 10% final tax to every villa-related payment
Regulation 34 of 2017 concerns qualifying land/building rental income. Management services are not automatically building rent.
Applying 2% Article 23 to building rental
DJP distinguishes rentals already subject to Article 4(2) from asset rentals within Article 23. Do not shift land/building rental into Article 23 merely because the rate differs.
Treating nightly villa rental as a building lease
Lodging services are excluded from Regulation 34 of 2017’s rental scope. Classify accommodation operations according to actual activities.
Combining rent and management fees in one amount
Combined invoices can make withholding bases difficult to identify. Separate components contractually and in accounting where they are different transactions.
Looking only at ledger account names
Tax classification follows transaction substance. Account codes assist administration but do not replace contract and party-relationship reviews.
When Is a Villa Tax Review Needed?
Deeper review is relevant when:
- An owner leases a villa to a corporate operator.
- A villa management agreement exists.
- The company pays management fees to another party.
- One contract covers property and services.
- Old invoices used Article 23 despite the transaction being a building lease.
- Building leases receive different treatment across periods.
- Vehicles or equipment are rented alongside the villa.
- The ledger differs from withholding certificates.
- Owner, operator and management transactions share one cash flow.
- The company faces a review, SP2DK enquiry or tax audit.
For Bali villa businesses, Usman Tax provides transaction recording and reconciliation, consultation and tax reporting support.
Conclusion
In villa lease vs management fee tax, comparing PPh Article 4(2) and Article 23 does not produce one answer for every transaction.
For genuine land/building rental, start with Regulation 34 of 2017 and final income tax. Management fees, other asset rentals or qualifying services to recipients within Article 23 require a different analysis.
A safer sequence is identify the transaction → identify parties → examine assets or services → determine the income tax basis → calculate withholding → match invoices, payments and the ledger. This prevents choosing a rate first and forcing transactions to fit it.
Unsure Which Income Tax Applies to Your Villa Transaction?
If a villa contract combines property rent, management fees, reimbursements or other asset use, separate components before determining the income tax type and issuing withholding certificates.
Usman Tax provides tax and accounting services for Bali hospitality businesses. Through its villa management tax reporting services, consultation can review contracts, invoices, the ledger and payment flows so tax classifications follow actual transactions.
FAQ Villa Lease vs Management Fee Tax
What is the main difference between Article 4(2) and Article 23 for villas?
Final Article 4(2) in this context applies to land/building rental income under Regulation 34 of 2017. Article 23 can cover asset rentals outside final income tax, management and consulting services and other qualifying services.
What is the income tax rate for villa building rental?
Regulation 34 of 2017 sets final tax at 10% of the gross land/building rental value for transactions within its scope.
Are villa management fees subject to Article 23?
Management services can be subject to Article 23 at 2% of gross amounts. Application still requires checking service substance, recipient and whether the payer has a withholding obligation.
Is nightly villa rental automatically subject to final building rental tax?
No. Regulation 34 of 2017 excludes lodging services and their accommodation from its land/building rental scope.
Does vehicle rental for villa operations fall under Article 23?
Article 23 covers rentals and other income from assets outside Article 4(2). Actual treatment depends on asset type, recipient and the payer’s withholding obligation.
What if one invoice includes villa rent and management fees?
Review the contract and each component’s substance. If they are different transactions, make their amounts and tax treatments separately traceable.
Sources and References
- Final Income Tax on Land and/or Building Rental — jdih.kemenkeu.go.id
- Official Explanation of PPh Articles 23 and 26 — stats.pajak.go.id
- Other Service Categories within PPh Article 23 — jdih.kemenkeu.go.id
- Usman Tax Bali Hotel and Villa Tax Review Guide — usmantax.co.id
- Usman Tax Bali Accounting Services — usmantax.co.id
Read Also: Villa Owner Statements: Reconciling Fees, Costs and Tax Payments