PPh 25 Instalments: Payment Periods and Evidence
Controls over PPh 25 instalments need to ensure that the tax period, instalment basis, payment code and payment evidence agree. Do not use a 2020 example as administrative guidance for a current tax period without reading the applicable rules.
Check the instalment basis
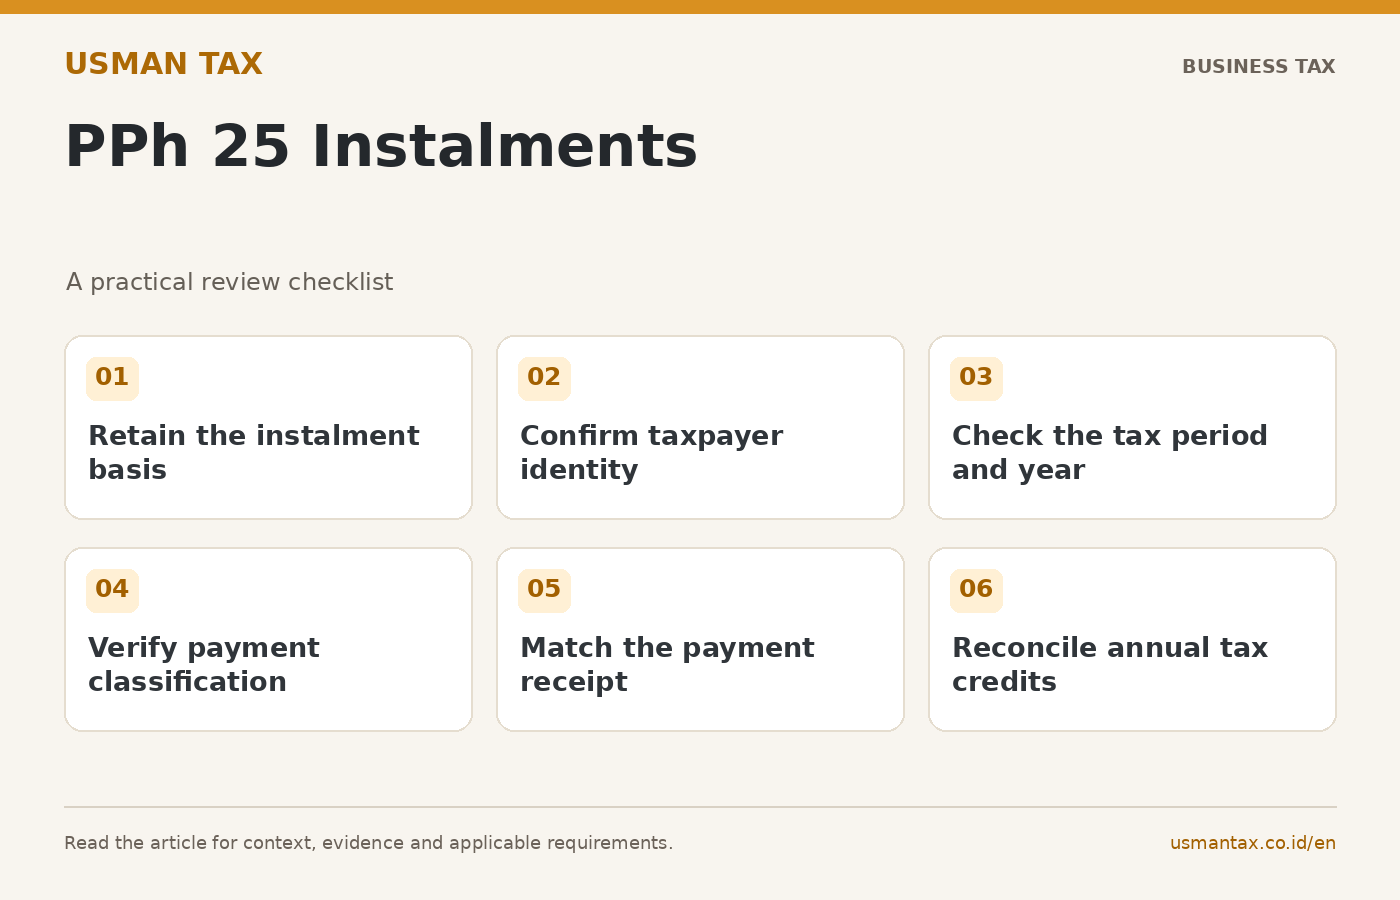
Match the instalment calculation to the tax documents and the taxpayer’s relevant circumstances. Changes or special provisions may require review. Retain the basis for the figures so monthly payments can be explained when annual tax credits are reconciled.
Confirm the payment period and identity
Check the taxpayer’s identity, period, year, payment type and amount before making payment. Evidence showing an incorrect period or code cannot automatically be used for the intended period. Evaluate the relevant correction procedure if an error is found.
Read the current administrative rules
PMK 81 of 2024 governs administration within the core tax system and has an amendment history, including PMK 1 of 2026 on the Ministry of Finance’s JDIH. Read deadlines and the treatment of payment evidence from the provisions relevant to that taxpayer and period. An old article should not be the sole basis for the calendar.
Retain evidence and a verifiable status
The archive includes calculations, billing codes, payment evidence and any necessary follow-up. Match the payment reference and period to the instalment schedule. Check reporting requirements or status against the applicable administrative rules; do not automatically assume that every payment requires the same separate filing process.
Connect the payments to the annual calculation
An instalment schedule helps trace tax credits, but their use in the annual tax return must still meet the rules. Match it to the annual tax working papers and PPh Article 29. This article focuses on evidence controls; specific deadlines that have not been verified are not presented as certain.
FAQ PPh 25 Instalments
Does a payment example from 2020 automatically apply today?
No. Check the administrative rules and amendments applicable to the relevant period.
What is the minimum check before payment?
Identity, tax period and year, code, amount and the basis of the instalment calculation.