PPh 23 Tax Rates: Classification and Exceptions
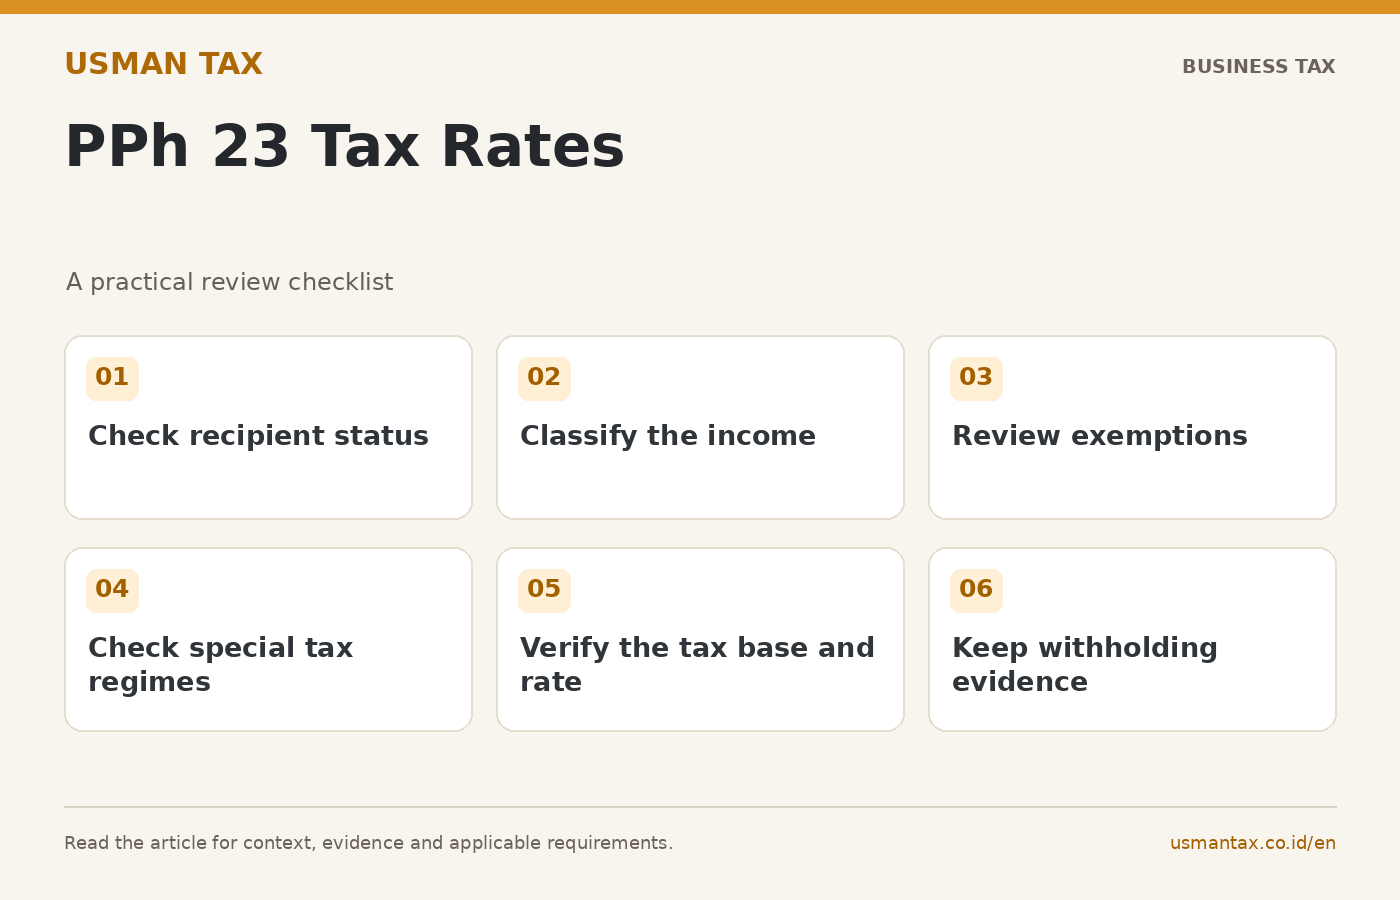
PPh 23 tax rates are determined after examining the income type, recipient and exemptions. Do not apply service withholding solely from the vendor’s name or assume that every construction service receives the same treatment.
Identify the recipient and nature of the payment
Check the recipient’s identity, domestic status, contract, invoice and income type. Payments for services, asset rentals, interest, royalties or dividends are not one identical group. Payments to individuals and overseas parties require their own examination.
Distinguish the rate groups
PPh 23 includes 15% and 2% rate groups, each subject to its own taxable-income and exemption tests. These figures are not an instruction to withhold from every invoice. For dividends, transactions subject to final tax and exempt income, check the relevant rules before applying a general rate.
Examine construction services and final tax
Income from construction services is governed by specific final income tax provisions. Do not copy a service list from an old article without reading the applicable sector rules. Review the contract, activities and qualifications to determine the basis for treatment.
Prepare the withholding basis and evidence
The working paper records the recipient’s identity, income category, tax base, determined rate, tax amount and supporting documents. Reimbursements and mixed invoice components require evidence. Payment and reporting requirements are examined separately from the income classification.
Use hospitality examples for application
For hotel and villa vendors, use the vendor classification guide. For fees paid to a domestic villa manager, use the management fee article. This guide introduces rates and exemptions; the result for an invoice must follow the actual documents.
FAQ PPh 23 Tax Rates
Is every service invoice subject to 2% withholding?
No. Check the recipient type, income category, exemptions and relevant tax regime.
Do construction services automatically fall under PPh 23?
Do not assume so. Review the final income tax rules for construction services and the activity documents.